Polish political leaders and industry stakeholders are disputing the future of the domestic vaping market as draft legislation UD363 reaches President Karol Nawrocki. While opponents frame resistance to the bill as protection for domestic businesses, official records show that foreign capital and Chinese manufacturing dominate the current supply chain.
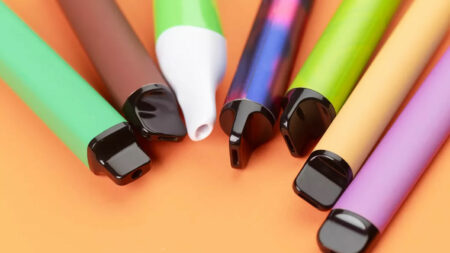
According to Ministry of Finance data, only 26 domestic entities manufacture e-cigarette liquids and pods within Poland. Data from the Market Monitoring Centre further reveals that nearly all disposable devices sold nationwide are imported directly from China. Consequently, debates surrounding excise definitions directly impact importers and global corporations rather than local industrial manufacturers.
Electromagnetic Induction Creates Multi-Million Tax Gap
The central fiscal dispute involves disparate tax treatments applied to competing technologies. Following excise revisions in September 2025, an international tobacco corporation introduced an e-cigarette system operating on electromagnetic induction. Because statutory tax definitions specifically targeted traditional resistance-coil systems, induction cartridges fell outside the legal classification for device excises.
This technical gap produced an asymmetric tax burden across equivalent consumer items:
- Traditional Systems: Cartridges faced an excise levy of 40 PLN per unit.
- Induction Systems: Cartridges entered the market without the corresponding 40 PLN device levy.
An industry analysis titled "Induction Deficit in E-Cigarette Excise" estimated that starter kits using induction technology averaged monthly sales exceeding 11,000 units. If taxed under identical terms with two cartridges per kit, the fiscal difference would generate approximately 10.56 million PLN per year in tax advantages for a single global brand.
| Product / Tax Category | Current Excise Framework | Proposed UD363 Framework |
|---|---|---|
| Base Hardware Unit | 40 PLN excise per device | 50 PLN excise per device |
| Traditional Coil Cartridge | 40 PLN device tax + liquid excise | Liquid excise only (0 PLN device tax) |
| Induction Cartridge | 0 PLN device tax (classification gap) | Liquid excise only (equal parity) |
| E-Liquid Rate (from 2027) | 1.80 PLN per milliliter | 2.20 PLN per milliliter |
UD363 Aims to Enforce Technological Neutrality
The Ministry of Finance designed UD363 to eliminate classification ambiguities, establishing that devices serving identical functions bear comparable levies regardless of internal heating mechanisms. The bill avoids piecemeal adjustments by revising statutory definitions across all vaporization categories.
Industry associations representing compliant businesses have urged the rapid adoption of market-wide rules during parliamentary proceedings:
“Pan minister w swoim wystąpieniu tak naprawdę większość czasu poświęcił uzasadnianiu projektu UD363, który przyjdzie zaraz, bo jest dobry, bo jest kompleksowy. No, widzimy to,” stated Wojciech Bronicki, President of BBGTAX Law Firm.
During parliamentary committee hearings, representatives from Employers of Poland (Pracodawcy RP), the Polish Economic Society (PTG), and the Polish Chamber of Commerce (KIG) called for broad regulatory reform. Jaromir Ćwikła of PTG stressed before the Senate that the sector requires a level playing field to prevent distortions caused by proprietary designs.
“Bardzo pozytywnie oceniam ten drugi projekt. Ma on niewątpliwie charakter generalny, abstrakcyjny i bez wątpienia kompleksowy w stosunku do całej branży,” stated Dr. Andrzej Tatara from the University of Zielona Góra during Senate proceedings.
Presidential Scrutiny and Consumer Price Adjustments
The measure now sits with President Karol Nawrocki, who previously challenged tobacco legislation in July 2026. At that time, President Nawrocki referred bill UD308 to the Constitutional Tribunal, citing short adjustment intervals and a narrow scope focused solely on induction methods. UD363 answers several procedural criticisms by adjusting definitions across the entire market, though executive approval remains pending.
For adult consumers, UD363 alters retail price dynamics. Although the hardware tax increases by 10 PLN to 50 PLN, and the e-liquid levy rises from 1.80 PLN to 2.20 PLN per ml in 2027, removing the 40 PLN cartridge excise reduces the net tax on a standard 2 ml pod by 39.20 PLN.
Black Market Pressures Challenge Fiscal Enforcement
Tax enforcement problems coincide with an expanding illicit market. National Revenue Administration (KAS) records document that agents conducted over 1,200 inspections during the first half of 2026 alone, seizing 424,400 illicit e-cigarettes and over 6.7 million milliliters of untaxed liquid.
While UD363 standardizes definitions across technical formats, business organizations note that regulatory clarity must operate alongside strict border inspections to protect compliant retailers from unregulated imports.
Vape Content Creator | Flavor Reviewer | Lifestyle & Vape Culture Editor
Emily Carter is a vape-focused content creator specializing in flavor reviews, device aesthetics, and lifestyle-oriented vaping content. With hands-on experience testing disposable vapes and pod systems, Emily delivers clear, visually driven insights designed for adult consumers.